Your Local Mortgage Lender
Located in Alabama
Personalized Mortgage Experience
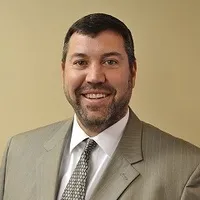
Scott Moulton offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Alabama.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates

How Much Do You Need for a Down Payment on a New House?
Home Buying Guide
How Much Do You Need for a Down Payment on a New House?
A complete guide to understanding down payments — from the bare minimum you can put down to the sweet spot that saves you the most money over time.
Saving for a down payment is one of the biggest milestones on the path to homeownership. For many first-time buyers, it's also one of the most confusing. You've probably heard that you need "20%" — but is that actually true? The short answer is no. The real answer is more nuanced, and understanding it could save you tens of thousands of dollars or help you get into a home years sooner than you thought.
This guide breaks down exactly how much you need, what loan programs are available to you, and how to think strategically about how much to put down.
What is a down payment, exactly?
A down payment is the portion of a home's purchase price that you pay upfront, out of pocket — as opposed to the amount you borrow through your mortgage. If a home costs $350,000 and you put down $35,000, you're putting down 10% and borrowing the remaining $315,000.
Your down payment directly affects several things: your monthly mortgage payment, your interest rate, whether you need mortgage insurance, and how much equity you start with in the home. The more you put down, the less risk the lender takes on — and the better the terms they typically offer you.
Down payment amounts are almost always expressed as a percentage of the home's purchase price, not a fixed dollar figure. That means what you need scales with the price of the home you're buying.
The minimum down payment by loan type
There is no single universal minimum — it depends entirely on which type of mortgage loan you qualify for. Here are the four main categories:
Most popular
Conventional Loan
3–20%
As low as 3% for first-time buyers. PMI required under 20%. Best rates at 20% down.
Military
VA Loan
0%
No down payment required for eligible veterans, active duty, and surviving spouses.
FHA
FHA Loan
3.5%
3.5% with a 580+ credit score. 10% if your score is 500–579. Easier to qualify.
Rural
USDA Loan
0%
Zero down for eligible rural and suburban buyers who meet income requirements.
As you can see, "you need 20% down" is a myth for many buyers. Millions of Americans buy homes every year with far less — and in some cases, nothing at all.
The 20% rule: myth or smart strategy?
The 20% figure didn't come from nowhere — it's rooted in real financial logic. When you put down 20% or more on a conventional loan, lenders consider the mortgage low-risk and reward you with better interest rates. More importantly, you avoid Private Mortgage Insurance (PMI), which is an extra monthly cost that protects the lender (not you) if you default.
PMI typically costs between 0.5% and 1.5% of your loan amount per year. On a $300,000 loan, that's $1,500–$4,500 annually — money that doesn't build any equity and simply disappears.
PMI isn't forever. On conventional loans, you can request removal once you've built 20% equity in the home — either through payments, appreciation, or home improvements. By law (the Homeowners Protection Act), lenders must cancel PMI automatically when your loan-to-value ratio reaches 78%.
So is 20% the "right" answer? It depends on your situation. If you have the savings and time, 20% gives you the best rates, no PMI, and lower monthly payments. But waiting to save 20% on a $400,000 home means accumulating $80,000 — which could take a decade in many housing markets. In the meantime, home prices may rise faster than you can save. Sometimes getting in the market sooner with a smaller down payment is the better long-term play.
What does a down payment actually cost at different price points?
Here's a practical look at what various down payment percentages look like in real dollar terms across different home prices:
Home Price3% Down5% Down10% Down20% Down$200,000$6,000$10,000$20,000$40,000$300,000$9,000$15,000$30,000$60,000$400,000$12,000$20,000$40,000$80,000$500,000$15,000$25,000$50,000$100,000$750,000$22,500$37,500$75,000$150,000
Keep in mind that these figures are just the down payment. You'll also need to budget for closing costs, which we cover below.
Don't forget closing costs
One of the most common mistakes first-time buyers make is saving only for the down payment and getting blindsided by closing costs. These are fees paid at the time of closing that cover things like the loan origination, appraisal, title insurance, escrow, and prepaid property taxes and insurance.
Typical closing cost range
2–5%
On a $350k home, that's
$7k–$17.5k
Often due at closing
All at once
Closing Cost ItemTypical CostLoan origination fee0.5–1% of loanAppraisal$300–$700Title insurance$500–$2,000Home inspection$300–$500Prepaid property taxesVaries by areaHomeowner's insurance (prepaid)$600–$1,500Attorney/settlement fees$500–$1,500
In some cases, you can negotiate for the seller to cover some or all of your closing costs — known as "seller concessions." This is more common in a buyer's market where sellers are motivated. You can also roll some costs into the loan, though this increases what you borrow.
How much should you actually put down? Scenarios that matter.
There's no universally "correct" answer — the right amount depends on your financial picture, your local market, and your goals. Here are a few common scenarios to help you think through your situation:
You want the lowest possible barrier to entry
If your goal is simply to get into homeownership as soon as possible — especially if rents are high and you're not building equity — a 3% or 3.5% down payment makes sense. Yes, you'll pay PMI, but you start building equity immediately and benefit from any appreciation.
You want to eliminate PMI without waiting for 20%
Putting down 10% won't eliminate PMI on a conventional loan, but it meaningfully reduces your loan balance and monthly payment. Some buyers use a "piggyback loan" (an 80/10/10 structure) to avoid PMI — 80% first mortgage, 10% second loan, 10% down payment.
You have strong savings and want the best rate
If you have the cash and want the optimal rate, lowest monthly payment, and no PMI, 20% is the benchmark. Some lenders offer slightly better terms at 25% or 30% down if you're in a high loan amount situation.
You're a veteran or in a rural area
If you qualify for a VA or USDA loan, putting anything down is optional. These programs exist precisely to make homeownership accessible to qualified buyers without large savings. You might still choose to put some money down to reduce your loan balance, but you're not required to.
You have the 20% but it would wipe out your savings
This is a critical scenario many buyers overlook. If putting down 20% means you have nothing left for emergencies, repairs, or moving costs, you're in a precarious position. A smaller down payment that leaves you with a financial cushion is often the wiser choice.
Down payment assistance programs
If saving feels impossible, you may not be as alone as you think. There are thousands of state, local, and federal programs designed to help buyers — especially first-timers — with down payment funds. These come in several forms:
1
Grants— Free money that doesn't need to be repaid. Often limited to first-time buyers under certain income thresholds. Check your state housing finance agency.
2
Forgivable loans— A second loan that is forgiven (usually after 5–10 years of living in the home) if you meet the terms. Effectively a grant if you stay long enough.
3
Deferred loans— A second loan with 0% interest that isn't due until you sell, refinance, or pay off the first mortgage. Helps bridge the gap now without immediate repayment.
4
Matched savings programs— Some nonprofits and banks match what you save toward a down payment — sometimes 3:1 or 4:1. Look for Individual Development Account (IDA) programs in your area.
5
Employer assistance— A growing number of large employers offer down payment assistance as a benefit. It's worth checking your HR department.
The HUD website (hud.gov) maintains a directory of housing counselors and approved down payment assistance programs by state. Many programs require a short homebuyer education course — usually a few hours online — as a condition of the award.
Can you use gift money for a down payment?
Yes — most loan programs allow gift funds from family members for all or part of your down payment. The key requirement is a "gift letter" from the donor stating that the money is truly a gift and does not need to be repaid. Lenders scrutinize large deposits in your bank account leading up to the mortgage application, so it's important to document everything properly and avoid loans disguised as gifts (lenders will ask).
For FHA loans, gift funds can cover the entire 3.5% down payment. Conventional loans may require that you contribute some of your own funds if the down payment is under 20%, depending on the lender and loan program.
How to save for a down payment: practical strategies
A
Open a dedicated high-yield savings account.Keep your down payment funds completely separate from your everyday spending. High-yield savings accounts (HYSAs) currently offer significantly better interest than traditional savings accounts.
B
Automate your savings.Set up an automatic transfer the day after your paycheck hits. Treat it like a bill you can't skip. Even $500/month grows to $18,000 in three years.
C
Tap your IRA.First-time homebuyers can withdraw up to $10,000 from a traditional IRA without paying the 10% early withdrawal penalty (though you'll owe income tax). Roth IRA contributions can be withdrawn at any time penalty- and tax-free.
D
Cut the biggest expenses first.Reducing rent by moving to a cheaper place or getting a roommate, or pausing car payments, typically yields far more than cutting lattes. Focus on your three largest monthly expenses.
E
Consider a side income specifically for the goal.Freelancing, part-time work, or selling unused items can accelerate savings dramatically. Treat every dollar earned from this stream as untouchable until closing day.
F
Set a specific target date."I want to buy a home" is a wish. "I need $28,000 by March 2027, so I must save $700/month for 40 months" is a plan. Reverse-engineer your timeline from your goal.
Frequently asked questions
Is it ever a bad idea to put more than 20% down?
Not necessarily — but it depends on opportunity cost. If you have investment accounts earning 7–10% annually and your mortgage rate is 6.5%, tying up extra cash in home equity may not be the most efficient use of your money. Equity in a home is not liquid; you need a home equity loan or sale to access it.
Does my credit score affect how much I need to put down?
Yes. For FHA loans, a credit score of 580 or above qualifies you for the 3.5% minimum. Scores between 500–579 require 10% down. For conventional loans, lower credit scores often require a larger down payment or result in higher PMI rates. The better your credit, the more options you have.
What happens if I put down less than 20% and prices drop?
If home prices fall significantly, you could end up "underwater" — owing more than the home is worth. This is more of a risk with very small down payments (3–5%) in volatile markets. It's one reason why maintaining a financial cushion beyond the down payment is important: it reduces the pressure to sell at a loss.
Can I use a 401(k) for a down payment?
Some 401(k) plans allow loans of up to 50% of your vested balance (max $50,000). Unlike IRA withdrawals, 401(k) loans must be repaid — typically within 5 years — or you'll owe taxes and penalties. Withdrawing (not borrowing) from a 401(k) incurs a 10% penalty plus income taxes, making it an expensive option except in rare circumstances.
Does the down payment affect my interest rate?
Yes, indirectly. A larger down payment means a lower loan-to-value ratio, which lenders view as less risky. This can translate into a modestly lower interest rate. The biggest jump in rate improvement typically comes when you cross the 20% threshold and eliminate PMI risk entirely.
The bottom line
There is no single right answer to how much you need for a down payment. The minimum can be as low as 0% (VA and USDA loans) or 3–3.5% for many first-time buyers through conventional and FHA programs. The traditional 20% benchmark eliminates PMI and secures better loan terms — but it's not a hard requirement, and waiting to hit it could mean missing years of homeownership and equity building.
The most important factors to weigh are: which loan programs you qualify for, what you can actually afford to put down without depleting your emergency fund, and how long you plan to stay in the home. A mortgage professional or HUD-approved housing counselor can help you model the exact tradeoffs for your situation.
Homeownership is one of the largest financial commitments you'll ever make — but it doesn't have to be out of reach. With the right loan, the right program, and the right savings strategy, that down payment goal is almost certainly closer than you think.
Want a personalized breakdown?
Tell me your target home price and current savings, and I'll calculate your down payment options across different loan types.
Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|
Important Pages
Terms of Service
Privacy Policy
Accessibility Assistance
State Licenses
UT#
Social Media Links
YouTube
